Reduce your tax burden while supporting Catholic education
It's not a figure of speech. The Education Freedom Tax Credit turns your tax liability into scholarships through a dollar-for-dollar federal credit of up to $1,700 a year - and $3,400 if married filing jointly - that sends a child to a Catholic school in your community. Not a deduction you write off. A credit you get back, in full.
DONATE starting JAN 1, 2027
Contribute to your school or diocese of choice
CLAIM THE CREDIT on your 2027 taxes
Receive your needed taxes documentation, claim the dollar-for-dollar credit on your return.
Help a child learn faithfully
A child at the school or diocese you selected receives a scholarship
A contribution used for the §25F federal credit cannot also be claimed as a federal charitable deduction. Any state tax credit allowed for the same contribution reduces the federal credit.
WHy give
Your gift can make a meaningful difference to children across the nation
Help Catholic families afford faithful education
Every child deserves to be formed in the Faith, but when it comes to education, private schools can become expensive, especially when paying for multiple children. The tax credit gives us a no net cost way to alleviate that burden for families across the nation.
Expand support for the disabled
Contributions can be used to provide special ed programs, assistive technology, occaptional, speech, and behavioral therapy, and more.
Sustain Catholic education in America
The new tax credit provides an unprecedented opportunity to build the long-term viability of these Catholic schools across the nation.
Any taxpayer can contribute to Catholic education and claim the tax credit in return (provided they meet eligibility requirements). If your state has not opted into the program, you can still contribute to a Catholic school in a state which has opted in.
THE OPPORTUNITY
How the Credit Works
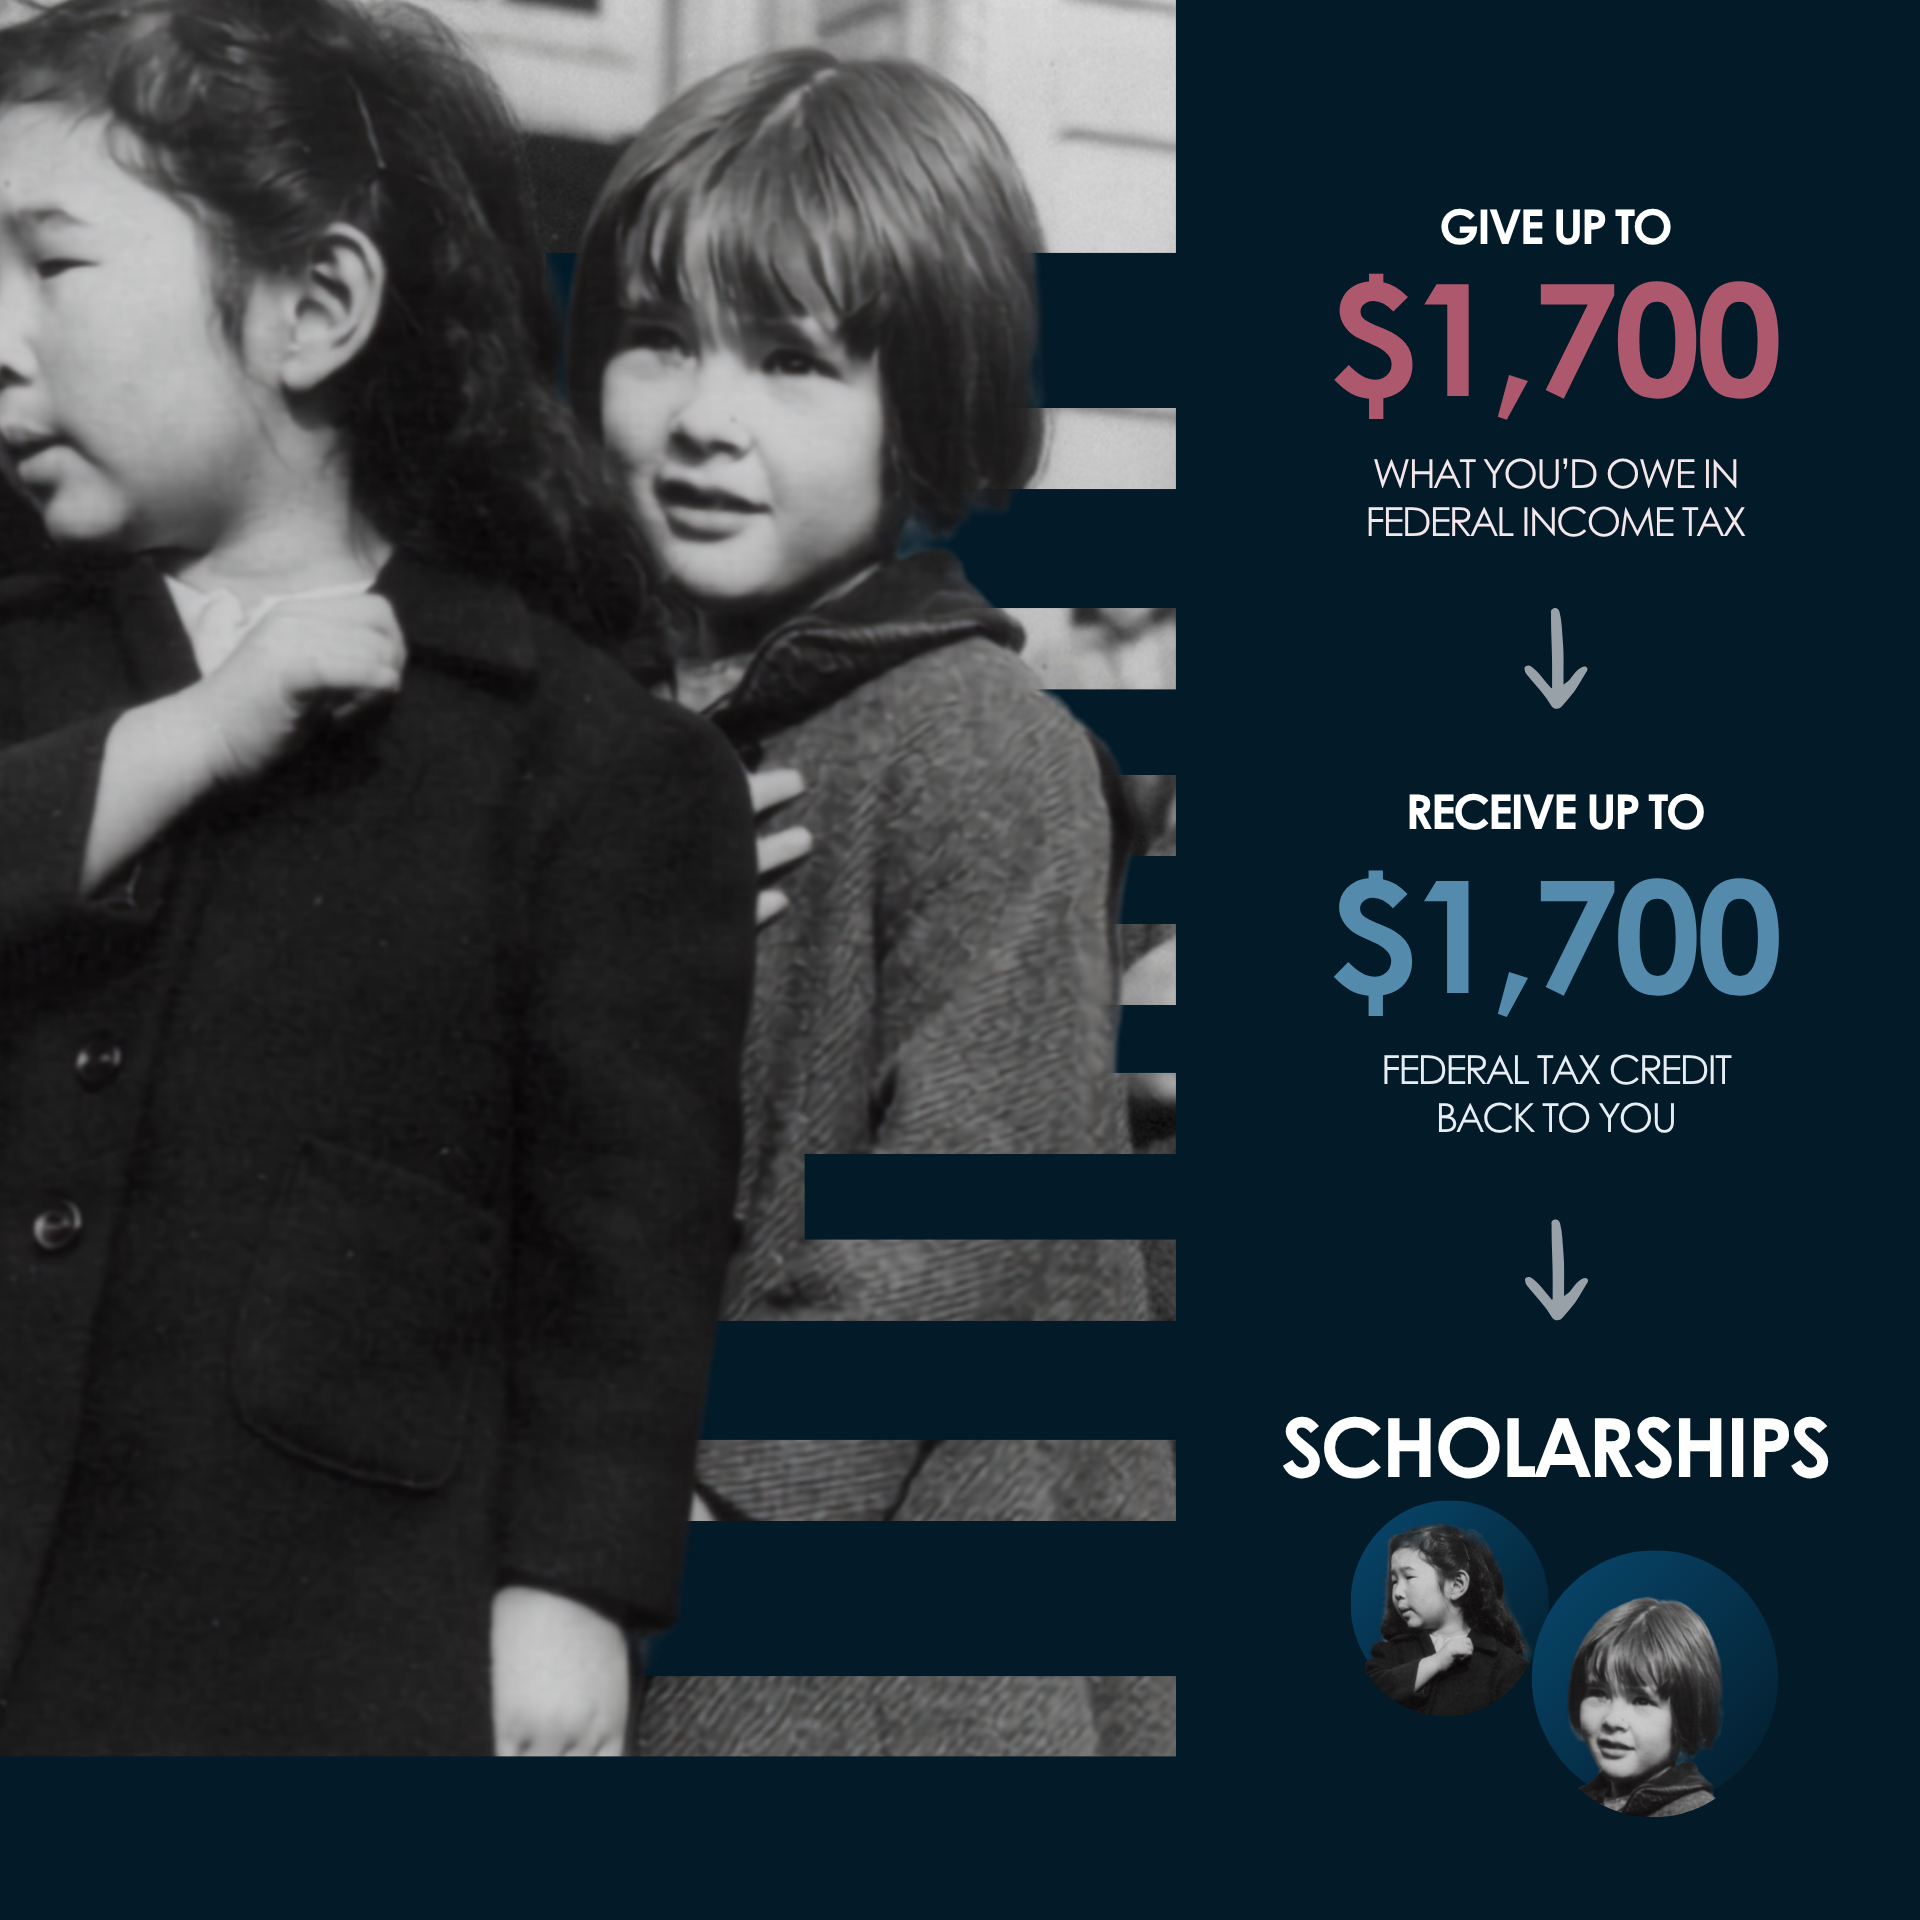
Qualifiying taxpayers give up to $1,700 to a scholarship granting organization (such as Catholic Education Fund), or $3,400 if married filing jointly, and receive a dollar-for-dollar tax credit back on their 2027 taxes.
States must opt-in to participate in the federal program.
~90% of students in opted-in states can receive these scholarships.
About your tax credit
Answers to your Questions
Does my contribution reduce my federal taxes dollar-for-dollar?
For a qualifying contribution, IRC §25F provides a federal income tax credit equal to the amount contributed, up to the federal limit. The credit is nonrefundable, so the amount you can use in a given year depends on your federal income tax liability. Unused credit may generally be carried forward for up to five years.
My spouse and I file jointly — how does that work?
Current federal law limits the §25F credit to $1,700 and $3,400 if married filing jointly for any taxpayer in a taxable year. Additional Treasury and IRS guidance may further clarify how the limit applies in certain filing situations.
Can I also claim a charitable deduction?
Not for the same contribution. If you claim the §25F credit for a qualified contribution, those same dollars cannot also be claimed as a federal charitable contribution deduction.
What if I receive a state tax credit for my contribution?
Any state tax credit allowed for the same qualified contribution reduces the amount of federal §25F credit available for that contribution.
Why does state participation matter?
For a contribution to qualify, the Scholarship Granting Organization must be listed by a state participating in the federal program for that year. ACE Scholarships and Catholic Education Fund will provide current information for participating schools and states.